


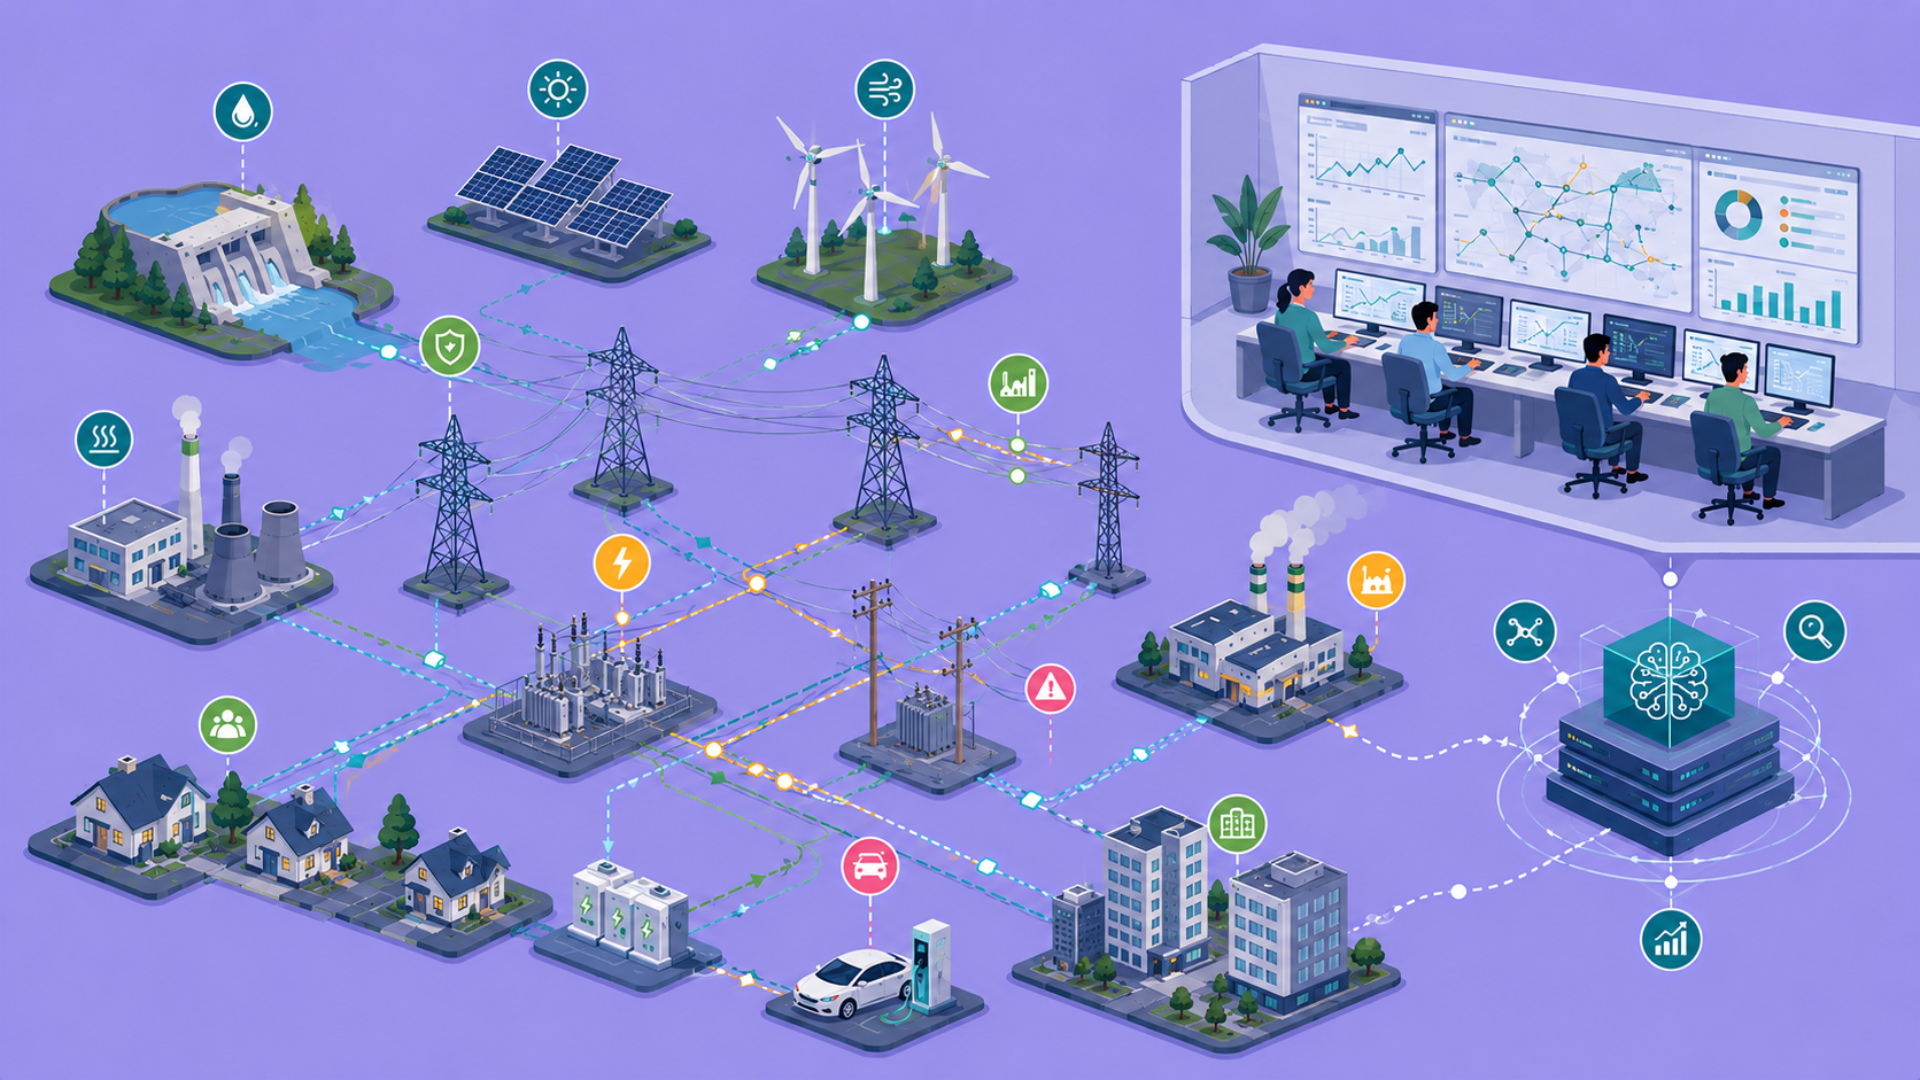
The energy sector in 2026 is under a convergence of pressures that makes the operational status quo untenable. Electricity demand in the United States is projected to grow at an average annual rate of 1.7%, with the commercial sector growing at 2.6% and the industrial sector at 2.1%. That demand is arriving from directions the grid was not designed to serve simultaneously: AI data centres requiring 176 gigawatts of capacity by 2035, electric vehicle charging infrastructure scaling across every major market, and industrial electrification driven by decarbonisation mandates.
The capital response to this demand is real and necessary. Deloitte estimates that more than $1.4 trillion will be needed through 2030, with roughly 2 terawatts of capacity in interconnection queues, nearly twice the capacity currently installed. But capital programmes operate on decade-long timelines. The operational gap between what the grid currently delivers and what it needs to deliver is arriving faster than steel, copper, and permits can close it.
AI is one of the few operational levers that moves on a 12-month timeline rather than a decade-long capital programme. It does not replace the infrastructure investment. It makes the existing infrastructure perform significantly better while that investment is being made.
The AI in energy and utilities market is growing from $4.54 billion in 2026 to $9.18 billion by 2030 at a 19.2% compound annual growth rate. 94% of power and utility CIOs plan to increase AI investments, with average spending increases of 38.3%. The investment is accelerating because the returns, in the deployments that have reached production, are specific and measurable.
The Four Deployments Generating Documented Returns
Predictive maintenance and asset health monitoring
Predictive maintenance is the energy sector AI use case with the most accumulated deployment evidence and the most consistent return. The economics are straightforward: an unplanned outage at a power generation facility or on transmission infrastructure costs orders of magnitude more than the maintenance intervention that would have prevented it. AI systems that identify developing failures three to four weeks before they become unplanned outages are changing the economics of asset management across the sector.
The predictive maintenance return comes through two mechanisms. The first is direct cost avoidance from preventing failures. This includes repair costs, lost generation revenue, and regulatory penalties from unplanned outages. These costs are avoided when failures are detected and addressed before they occur. The second is optimising planned maintenance scheduling. AI systems that know the health of every asset can schedule maintenance based on actual condition rather than the calendar. They can extend maintenance intervals for assets performing well and bring forward interventions for assets showing early signs of deterioration.
Predictive maintenance in energy deployments pays back in 12 to 18 months on average. Energy management AI more broadly reduces costs by 12 to 20%. These are not projected returns. They are reported outcomes from live deployments across utilities and large industrial energy consumers.
Gartner projects that 40% of power and utilities will deploy AI-driven operators in control rooms by 2027. The control room AI is not replacing operators. It gives operators access to patterns across the full network that no human team could identify manually. AI can detect sensor patterns that precede failures and surface them for operator attention before a failure occurs.
Grid optimisation and demand response
Renewable energy integration is the operational challenge that is driving the most urgent AI investment in grid management. Renewable generation like solar and photovoltaic is intermittent and increasingly dominant in the generation mix. Renewables are set to surpass coal-fired generation in 2026. Balancing a grid where generation variability is increasing requires a level of real-time optimisation that traditional grid management approaches cannot achieve.
AI systems can manage grid dispatch in real time. They continuously adjust generation, battery charging and discharging, and demand response as renewable output changes. This can support higher renewable penetration without a proportional increase in backup capacity. The International Energy Agency estimates that AI could reduce curtailment of renewable energy by up to 10% globally, which is significant given the scale of renewable investment currently in deployment.
Demand response is a specific application where AI is moving from analytics to autonomous action. AI systems can predict demand peaks, identify flexible loads that can be shifted without affecting customers, and automatically trigger demand response signals across commercial and industrial customers. This can reduce peak load requirements and defer or avoid the need for additional peaking capacity.
Energy forecasting and procurement optimisation
Large industrial and commercial energy consumers — manufacturers, data centre operators, large commercial real estate portfolios — face energy cost volatility that significantly affects their operational economics. AI forecasting systems can predict energy demand at the facility level. Combined with AI-powered energy procurement, they can optimise the mix of contracted and spot market purchases. This can reduce energy costs for large consumers.
AI can improve energy demand forecasting, especially for facilities with variable production schedules. These facilities often have complex relationships between production activity and energy demand. Better forecasts can reduce procurement errors, such as buying too much at contracted rates or too little and paying higher spot prices.
For utilities, AI demand forecasting at the grid level is improving the accuracy of capacity planning and reducing the frequency and magnitude of forecast errors that result in either excess capacity costs or reliability events. The combination of better demand forecasting and AI-optimised dispatch is changing the economics of grid operations in ways that flow through to both utility financial performance and consumer pricing.
Field workforce and asset management
The energy sector operates one of the largest field workforces of any industry. Lineworkers, technicians, engineers, and inspectors maintain infrastructure across enormous geographic areas, in conditions that range from routine to hazardous, on asset bases that are aging faster than they are being replaced.
AI applications in field workforce management for energy and utilities are following a similar path to field service management in manufacturing and consumer electricals OEMs. These include AI-driven job allocation that matches technician skills and certifications to job requirements, predictive maintenance that prioritises interventions based on asset condition, and mobile-first job management that works reliably in the connectivity conditions field crews actually face.
GE Vernova's acquisition of Alteia to enhance AI tools for grid infrastructure monitoring and inspection is a specific signal that AI for grid inspection and situational awareness is being productised by major incumbents. Computer vision systems can analyse drone and satellite imagery to detect vegetation encroachment, conductor damage, and structural deterioration across transmission and distribution infrastructure. This reduces reliance on manual inspection programmes that cannot keep pace with the scale of the network.
The Operating Model Shift AI Is Enabling
The energy sector's AI trajectory in 2026 points toward a fundamental shift in how utility operations are managed — from periodic human-directed processes to continuous AI-monitored operations with human oversight at defined exception thresholds.
Deloitte's 2026 Power and Utilities Outlook describes this as AI enabling real-time optimisation of dispatch, asset performance, and outage response. The operational model that enables this is different from the operational model that most utilities currently run. It requires continuous data from connected assets, real-time integration between operational and information technology systems, and clear governance over AI actions. This defines what AI can do autonomously and what requires human approval.
The operational technology and information technology convergence is the infrastructure prerequisite that most utilities are investing in now. Sensors, communication networks, and data platforms give AI real-time visibility across the asset base. Without them, AI relies on periodic reports from disconnected systems and cannot perform as designed.
This is the same data infrastructure prerequisite that enterprise AI deployment requires in every sector. The AI is only as good as the data it can access, and in energy and utilities the data is often locked in operational technology systems that were not designed to share it with analytics and AI platforms in real time.
The Specific Challenge of Regulated Environments
Energy and utilities is one of the most heavily regulated sectors in any major economy. AI deployments that affect grid operations, customer billing, or critical infrastructure management operate under regulatory frameworks that impose specific requirements on how AI decisions are made, documented, and audited.
The forward deployed engineering approach to regulated industry deployments applies directly to energy and utilities. Governance built into the deployment from day one is essential. This includes audit trails, explainability documentation, and human oversight at defined decision points. It allows AI to operate within the regulatory framework and reduces compliance risk.
Utilities moving fastest on AI deployment are building governance and regulatory requirements into the AI architecture before development begins. They treat regulatory review as part of the deployment process, not as a post-deployment gate. The result is that deployments pass regulatory review without the rework cycles that are common when governance is retrofitted.
What the Next 18 Months Look Like
The energy sector AI investment trajectory is accelerating for reasons that are structural rather than cyclical. The growth in AI data centres and EV charging, the shift to renewable energy, aging infrastructure, and the retirement of experienced engineers are creating new operational pressures. AI is well positioned to address many of these challenges.
CenterPoint's $65 billion capital spending plan for 2026 to 2035, tied explicitly to load growth expectations from data centres and AI, is representative of the capital commitment being made across the sector. The AI operational layer helps this capital investment perform better. It optimises existing assets, manages demand response, and enables predictive rather than reactive maintenance. This layer is being built alongside the physical infrastructure.
The enterprises that are getting ahead in energy sector AI are not the ones waiting for the technology to mature further. The technology is mature enough. The key constraints are data infrastructure, operational technology integration, and a governance framework that allows AI to operate reliably. In a sector where reliability is measured in nines, failures can have consequences far beyond a single organisation.
Vishleshan AI works with enterprises in the energy and utilities sector to deploy production AI across operations and supply chain, field service management, and asset and workforce intelligence, using forward deployed engineers who build AI inside client environments with the governance architecture that regulated operations require. Book a Consultation